
Florida condo insurance helps protect the parts of your condominium unit, personal belongings, liability exposures, and other financial risks that may not be covered by your condominium association’s master insurance policy.
Often written on an HO-6 condominium unit-owner policy, condo insurance can help cover interior property and improvements you are responsible for, personal property, additional living expenses after a covered loss, personal liability, medical payments, and certain loss assessments. The right coverage depends in part on what your condominium association insures, what you are responsible for as a unit owner, how the condo is occupied, and the specific terms of the policies involved.
For Florida condo owners, those distinctions are especially important because hurricanes, windstorm deductibles, water losses, flood exposure, association assessments, and differences between association and unit-owner responsibilities can create significant gaps when coverage is not coordinated properly.
Interactive Graphic

Betterments and Improvements
Risk Factor
Any betterments, improvements, alterations, or additions made to your condominium are subject to damage. However, it’s important to make sure they’re covered appropriately.
Solution
Be sure to obtain coverage for any betterments, improvements, alterations, and additions made to the unit. This includes, but is not limited to, kitchen cabinets, built-in wall units, wall-to-wall carpeting, wallpaper, paint, bathroom fixtures, tile and wood flooring, and more.
Personal Property
Risk Factor
Unpredictable losses can occur to your property due to burglary, fire, water damage, storm, and more.
Solution
Personal property, such as furniture, rugs, TVs, stereos, clothes, and more may be covered under your basic insurance policy. However, items like jewelry, furs, silverware, antiques, collectibles, and other valuables should likely be insured separately.
Additional Living Expenses
Risk Factor
Additional living expenses can be incurred if there is damage to your unit due to a fire, storm, or other event resulting in your need to live at a temporary residence.
Solution
Ensure you have the proper coverage in case you need to live elsewhere for a little while. Coverage usually includes hotel bills, restaurant meals, and other living expenses incurred while your residence is being repaired or rebuilt.
Personal and Family Liability
Risk Factor
You're responsible if a guest in your unit trips and falls or sustains an injury while on your property or if you cause damage to other units.
Solution
Be sure that you have coverage for claims made against you for bodily injury or property damage caused by your negligence, whether intentional or not. This might include damage to other units in the building, perhaps caused by a leaking pipe in your unit or otherwise.
Medical Expenses
Risk Factor
You're responsible if a guest is injured while on your property and you may be required to pay their medical expenses.
Solution
Ensure your insurance policy covers this risk. In the event a person is injured in your unit, he or she can submit medical bills to your insurance company. Medical expenses are usually paid without a liability claim being filed against you, with typical limits ranging from $1,000 to $5,000.
Loss Assessment
Risk Factor
If your building owner or association suffers a loss and doesn't have adequate insurance coverage of their own, they may require you to help pay for the loss via an assessment.
Solution
Consider loss assessment coverage to protect yourself in the event of an assessment caused either by a property (building) or liability loss. A range of limits may be available.
Physical Damage
Risk Factor
Physical damage can happen in many ways. As one example, suppose a fire unexpectedly breaks out in the utility closet and consumes the building causing significant damage.
Solution
Be sure your condominium owner, association, or corporation carries a comprehensive policy to cover the risk of physical damage. It’s important to know what the policy includes and what it doesn’t, which could range from covering just the shell of the building to including things like floors and walls.
What Is Florida Condo Insurance (HO-6)?
Florida condo insurance is a policy designed primarily for people who own an individual condominium unit. It is commonly written on an HO-6 policy form and is intended to work alongside—not replace—the insurance maintained by the condominium association.
The condominium association’s master policy generally insures certain portions of the building and common property, while the unit owner may be responsible for parts of the residence, personal belongings, liability exposures, and other losses that fall outside the association’s coverage.
Depending on the policy and coverage selected, an HO-6 policy may include protection for:
-
Interior building property and improvements for which the unit owner is responsible
-
Furniture, clothing, electronics, and other personal property
-
Additional living expenses if a covered loss makes the condo temporarily uninhabitable
-
Personal liability if the insured is legally responsible for injury or property damage to someone else
-
Medical payments to others
-
Certain loss assessments charged by the condominium association after a covered event
A condo policy should not be selected based only on the purchase price or market value of the unit. The amount and type of coverage needed can depend on the condominium documents, the association’s insurance policy, the unit’s interior finishes and upgrades, the owner’s personal property, occupancy, location, and the coverage limits and exclusions in the HO-6 policy.
For Florida condominium owners, reviewing both the association’s insurance responsibilities and the unit owner’s responsibilities is an important part of building the right insurance program.
Who Needs Condo Insurance in Florida?
Condo insurance is generally designed for people who own an individual condominium unit. The appropriate policy and coverage can vary depending on how the unit is occupied and whether it is a primary residence, second home, or rental property.
Owner-Occupied Condominiums
If you own and live in your condominium as your primary residence, an HO-6 policy can help protect the portions of the unit you are responsible for, your personal belongings, additional living expenses, personal liability, and other covered exposures that may not be insured by the condominium association.
Second Homes and Seasonal Condos
Florida has many condominiums used as vacation homes, seasonal residences, or second homes. These properties may have different underwriting considerations because they can be unoccupied for extended periods.
Coverage should reflect how frequently the condo is occupied, who has access to it, whether it is monitored while vacant, and any requirements imposed by the insurance company.
Condos Used as Rental Properties
If you own a condo and rent it to tenants, the insurance needs can be different from those of an owner-occupied unit. The policy should accurately reflect the rental use and may need to address the owner’s building property, furnishings provided with the unit, liability exposures, and potential loss of rental income.
Short-term or vacation rentals can create additional considerations and should be disclosed to the insurance company because not every condo policy is designed for short-term rental activity.
Renters Who Live in a Condominium
A person who rents a condominium from the unit owner generally does not need an HO-6 condo unit-owner policy. Instead, the tenant would typically consider renters insurance to help protect personal belongings, personal liability, and additional living expenses.
The fact that the residence is located in a condominium building does not make the tenant responsible for insuring the ownership interest in the unit.
The Association’s Insurance Does Not Replace the Unit Owner’s Policy
Even when a condominium association maintains a master insurance policy, an individual unit owner can still have significant uninsured exposures. The association’s policy and the unit owner’s policy are intended to address different property and liability interests.
Understanding who owns the unit, how it is occupied, and what the association is responsible for insuring is the starting point for determining the appropriate condo insurance coverage.
Condo Insurance vs. the Condominium Association’s Master Policy
A Florida condominium owner typically has two different layers of insurance to consider: the condominium association’s master insurance policy and the individual unit owner’s condo insurance policy. They protect different property and exposures, and one does not automatically replace the other.
The condominium association generally insures the common elements, association property, and portions of the condominium property that Florida law requires the association to insure. For residential condominiums, Florida law requires the association’s property policy to cover certain portions of the condominium as originally installed or replaced with like kind and quality, subject to specific statutory exclusions.
The association’s required property coverage generally excludes certain property located within the unit and serving only that unit, including:
-
Personal property
-
Floor, wall, and ceiling coverings
-
Electrical fixtures
-
Appliances
-
Water heaters and water filters
-
Built-in cabinets and countertops
-
Curtains, blinds, drapes, and similar window treatments
Under Florida law, insurance for these excluded items is generally the unit owner’s responsibility.
An individual HO-6 condo policy can help address those unit-owner exposures and may also provide coverage for personal belongings, additional living expenses, personal liability, medical payments to others, and certain loss assessments, depending on the policy and coverage selected.
Why Both Policies Need to Be Reviewed
A condo owner should not assume that the association’s master policy will restore everything inside the unit after a covered loss. At the same time, the HO-6 policy should not be structured without understanding what the association already insures.
The condominium declaration, bylaws, association insurance policy, HO-6 policy, and circumstances of the loss can all affect which policy responds and who is responsible for repairs or replacement.
For that reason, coordinating the unit owner’s coverage with the association’s insurance is one of the most important parts of reviewing Florida condo insurance.
Florida’s statutory division of insurance responsibility is set out in Florida Statute §718.111(11).
What Does Florida Condo Insurance Cover?
A Florida condo insurance policy can provide several types of protection for the unit owner, but the exact coverage depends on the policy form, limits, endorsements, exclusions, and how the condominium association’s master policy is structured.
A typical HO-6 policy may include coverage for:
-
Building property within the unit that the owner is responsible for, such as certain interior fixtures, finishes, cabinets, countertops, flooring, and improvements
-
Personal property such as furniture, clothing, electronics, household goods, and other belongings
-
Additional living expenses if a covered loss makes the condo temporarily uninhabitable
-
Personal liability if the insured is legally responsible for bodily injury or property damage to someone else
-
Medical payments to others for certain minor injuries, regardless of fault
-
Loss assessment coverage for certain assessments charged by the condominium association after a covered loss
-
Additional coverage for valuable property when higher limits or scheduled coverage are purchased for items such as jewelry, art, collectibles, or certain electronics
Coverage Depends on the Cause of Loss
Having condo insurance does not mean every type of damage is covered. Coverage usually depends on what caused the loss and whether that cause is insured under the policy.
For example, damage from a covered fire may be treated very differently from damage caused by flooding, wear and tear, repeated leakage, neglect, or an excluded type of water loss.
The Association’s Policy Still Matters
The HO-6 policy is only part of the overall insurance picture. Before deciding how much condo insurance to purchase, it is important to understand what the condominium association is responsible for repairing or replacing and what remains the unit owner’s responsibility.
That is why condo coverage should be reviewed together with the association’s insurance documents rather than selected in isolation.
What Is the Condo Association Responsible for Insuring in Florida?
For most residential condominiums in Florida, the condominium association is responsible for maintaining property insurance on the portions of the condominium that Florida law requires the association to insure.
Under Florida Statute §718.111(11), the association’s property insurance generally provides primary coverage for:
-
Portions of the condominium property as originally installed, or replacement of like kind and quality
-
Common elements and association property
-
Certain alterations or additions made to condominium or association property in accordance with Florida condominium law
Florida law also requires the association to use its best efforts to obtain and maintain adequate property insurance for the association, common elements, association property, and other condominium property that must be insured by the association.
Common Examples of Association-Insured Property
Depending on the condominium and its governing documents, association-insured property may include items such as:
-
The building’s structural components
-
Roofs and exterior walls
-
Common hallways and stairways
-
Elevators
-
Clubhouses and other association-owned structures
-
Shared mechanical systems
-
Certain originally installed components of individual units that Florida law places within the association’s insurance responsibility
The exact division of responsibility should be confirmed by reviewing the condominium declaration, association insurance policy, and applicable Florida law.
Important Exceptions
Florida law specifically excludes several categories of property from the association’s required property coverage when those items are located within a unit and serve only that unit. These exclusions generally include personal property, floor, wall and ceiling coverings, electrical fixtures, appliances, water heaters, water filters, built-in cabinets and countertops, and window treatments. Those items are generally the responsibility of the unit owner to insure.
There can also be exceptions for certain freestanding condominium buildings when the declaration places the insurance responsibility on the individual unit owner.
Because condominium insurance responsibility can be affected by the declaration, bylaws, association policy, amendments, and the circumstances surrounding a loss, unit owners should avoid relying only on a general “walls-in” or “walls-out” description.
What Is the Florida Condo Unit Owner Responsible for Insuring?
Florida condominium law places responsibility for certain property inside the unit on the individual unit owner rather than the condominium association.
Under Florida Statute §718.111(11), the association’s required property coverage generally excludes property located within the unit and serving only that unit, including:
-
Personal property
-
Floor coverings
-
Wall coverings
-
Ceiling coverings
-
Electrical fixtures
-
Appliances
-
Water heaters
-
Water filters
-
Built-in cabinets
-
Countertops
-
Curtains, blinds, drapes, and similar window treatments
Insurance for these items is generally the responsibility of the unit owner.
What This Can Mean After a Loss
A major fire, hurricane, or water loss can damage both property insured by the condominium association and property that belongs within the unit owner’s insurance responsibility.
For example, the association may be responsible for certain structural portions of the building, while the unit owner may be responsible for replacing damaged flooring, cabinets, countertops, appliances, interior finishes, and personal belongings.
That distinction is one reason an HO-6 policy should not be viewed simply as insurance for furniture and clothing.
Improvements and Upgrades Can Increase the Exposure
A condo owner who installs upgraded flooring, custom cabinets, higher-end countertops, lighting, built-ins, or other interior improvements may have significantly more property to insure than someone with basic finishes.
Coverage should therefore reflect the actual cost to repair or replace the portions of the unit for which the owner may be responsible, not simply the market value of the condominium.
Review the Association Documents and Master Policy
Florida law provides an important framework, but the association’s declaration, bylaws, insurance policy, and the circumstances of a particular loss can still affect how responsibility is handled.
For that reason, condo owners should review both their HO-6 policy and the association’s insurance documents when determining how much building property coverage they may need.
 Florida condo insurance is designed to work alongside the association’s master policy, with each policy addressing different property and exposures.
Building Property, Additions, and Alterations
One of the most important parts of a Florida HO-6 condo policy is Coverage A, which can help insure certain building property inside the unit that is the owner’s responsibility.
Florida law generally leaves several interior items to the unit owner to insure, including floor, wall, and ceiling coverings, electrical fixtures, appliances, water heaters, built-in cabinets and countertops, and similar property located within the unit and serving only that unit.
Depending on the policy and the condominium documents, Coverage A may help insure items such as:
-
Flooring, including tile, wood, laminate, or carpet
-
Built-in cabinets and countertops
-
Interior wall and ceiling finishes
-
Permanently installed fixtures
-
Certain built-in appliances
-
Interior doors and trim
-
Custom closets and built-ins
-
Renovations, upgrades, and improvements made to the unit
-
Other building property for which the unit owner is responsible
Improvements Can Significantly Increase the Amount You Need
The appropriate Coverage A limit should reflect more than the condo’s original finishes.
If you replace basic flooring with premium tile or hardwood, install custom cabinetry, remodel a kitchen or bathroom, add built-ins, or make other substantial improvements, the cost to restore the unit after a major covered loss can increase considerably.
Florida’s Department of Financial Services specifically advises condo owners to make sure their policy limits are updated when interior additions or upgrades are completed.
Coverage A Is Not Based on the Condo’s Market Value
The amount of building property coverage needed is generally not the same as the condo’s purchase price or market value.
Instead, the focus should be on the estimated cost to repair or replace the interior building property and improvements for which the unit owner may be responsible after a covered loss.
A condo worth several hundred thousand dollars could require relatively modest Coverage A if much of the building is the association’s responsibility, while another unit with extensive custom finishes and renovations could require substantially more.
Review Coverage A Alongside the Association Policy
The association’s master policy and the HO-6 policy should be reviewed together.
If the association insures certain property, the unit owner may not need to duplicate that same exposure. Conversely, if important interior property falls outside the association’s coverage, an inadequate Coverage A limit can leave the owner responsible for a significant portion of the reconstruction cost.
That is why estimating Coverage A carefully is one of the most important parts of building a Florida condo insurance policy.
How Much Building Property Coverage Should a Condo Owner Carry?
The amount of building property coverage a Florida condo owner should carry depends on the estimated cost to repair or replace the portions of the unit for which the owner may be responsible, not the condo’s market value.
For many unit owners, this means considering the replacement cost of interior finishes, fixtures, built-ins, appliances, and improvements that may not be covered by the condominium association’s master policy.
Items to Consider When Estimating Coverage A
The appropriate limit may need to account for the cost to replace or restore items such as:
-
Flooring
-
Built-in cabinets
-
Countertops
-
Interior wall and ceiling finishes
-
Permanently installed fixtures
-
Built-in appliances
-
Interior doors and trim
-
Custom closets and built-ins
-
Bathroom and kitchen upgrades
-
Other renovations or improvements
A unit with builder-grade finishes may have very different reconstruction costs from a similar-sized condo with custom cabinetry, premium flooring, stone countertops, upgraded bathrooms, and extensive built-ins.
Do Not Rely Only on the Association’s Master Policy
A common mistake is assuming that the association will rebuild the entire interior of the condo after a major covered loss.
The association may be responsible for certain parts of the building, while the unit owner remains responsible for other interior property. An HO-6 policy with too little Coverage A can leave the owner paying a significant portion of the repair or replacement cost personally.
Review Coverage After Renovations
Coverage should be reviewed whenever substantial improvements are made to the unit.
A kitchen remodel, new flooring, upgraded bathrooms, custom cabinetry, or other improvements can increase the amount required to restore the condo after a covered loss.
Replacement Cost Estimates Matter
When selecting a Coverage A limit, the goal is to estimate what it could cost to rebuild the unit owner’s portion of the interior using comparable materials and workmanship.
Construction costs, labor, materials, unit access, building rules, and local conditions can all affect the actual cost of repairs.
For that reason, condo owners should periodically review their building property limit rather than leaving the same amount in place year after year without considering changes to the unit or reconstruction costs.
 Flooring, cabinets, countertops, fixtures, appliances, and other interior improvements can significantly affect the amount of building property a condo owner needs to insure.
Personal Property Coverage
Personal property coverage can help protect the belongings you own inside your condominium, subject to the policy’s covered causes of loss, limits, deductibles, and exclusions.
This coverage is separate from the building property protection discussed in the previous sections. While Coverage A may apply to certain parts of the condo interior, personal property coverage generally applies to movable belongings that you own.
Examples can include:
-
Furniture
-
Clothing
-
Electronics
-
Computers and tablets
-
Kitchenware
-
Small appliances
-
Bedding and household goods
-
Sports equipment
-
Tools
-
Décor and furnishings
-
Other personal belongings
How Much Personal Property Coverage Do You Need?
The right amount depends on what it would cost to replace your belongings after a major covered loss.
A useful way to estimate this is to think room by room and consider what you would need to replace if the contents of the condo were damaged or destroyed. Furniture, electronics, clothing, kitchen items, and other everyday property can add up quickly.
Keeping a home inventory with photos, receipts, model numbers, or other documentation can also make it easier to estimate appropriate limits and support a future claim.
Some Property Has Special Limits
Certain categories of personal property may be subject to lower policy limits or special restrictions.
Depending on the policy, this can include items such as:
-
Jewelry
-
Watches
-
Fine art
-
Collectibles
-
Firearms
-
Money
-
Securities
-
Business property
-
Certain electronics or specialty equipment
If you own valuable property, the standard personal property limit may not provide the type or amount of protection you want. Additional coverage or scheduled personal property may be available for eligible items.
Property Away From the Condo
HO-6 policies may also provide some protection for personal property while it is temporarily away from the insured residence, subject to the policy terms and applicable limits.
The amount of off-premises coverage and the circumstances in which it applies can vary, so it is important to review the policy rather than assume all belongings are covered everywhere.
Personal Property Coverage Should Be Reviewed Periodically
Over time, people accumulate new furniture, electronics, jewelry, equipment, and other belongings. Significant purchases, renovations, or lifestyle changes can make an old personal property limit inadequate.
Reviewing the limit periodically helps make sure the policy continues to reflect what you actually own.
Replacement Cost vs. Actual Cash Value for Personal Property
When reviewing personal property coverage on a Florida condo policy, it is important to understand whether covered belongings are settled on a replacement cost or actual cash value basis.
The difference can have a major impact on how much you receive after a covered loss.
Replacement Cost
Replacement cost coverage generally pays the cost to replace covered personal property with new property of similar kind and quality, subject to the policy terms, limits, deductibles, and any applicable conditions.
For example, if a five-year-old television is destroyed in a covered loss, replacement cost coverage may help pay for a comparable new television rather than reducing the settlement for age and depreciation.
Actual Cash Value
Actual cash value generally reflects the value of the property at the time of loss after depreciation is considered.
That means older furniture, electronics, appliances, clothing, and other belongings may result in a lower settlement than the amount needed to buy comparable new items.
Why the Difference Matters
A policy with actual cash value settlement can be less expensive, but it may leave a larger out-of-pocket gap after a major loss.
Replacement cost coverage can provide stronger protection for many condo owners because the goal is to help replace damaged or destroyed belongings rather than reimburse only their depreciated value.
Some Policies Pay Replacement Cost in Stages
Depending on the policy, a claim may initially be settled on an actual cash value basis, with additional replacement cost benefits paid after the damaged property is actually repaired or replaced.
The timing, documentation requirements, and deadlines can vary by insurance company and policy form.
For that reason, condo owners should review not only the personal property limit, but also how the policy values covered property after a loss.
Additional Living Expenses and Loss of Use
If a covered loss makes your condominium temporarily uninhabitable, Loss of Use coverage can help with certain extra expenses you incur while your home is being repaired.
This coverage is important because a serious fire, water loss, hurricane, or other covered event can force a condo owner to live somewhere else for days, weeks, or even longer.
What Additional Living Expenses May Include
Depending on the policy and circumstances, covered expenses may include reasonable increases in costs such as:
-
Temporary housing or hotel expenses
-
Short-term rental costs
-
Additional meal expenses
-
Laundry expenses
-
Extra transportation costs
-
Pet boarding
-
Storage expenses
-
Other necessary increases in normal living costs
The purpose is generally to help you maintain a comparable standard of living while the insured condo is not fit to live in because of a covered loss.
It Does Not Pay Every Expense
Loss of Use coverage generally does not pay all of your normal household expenses or reimburse costs that would have existed even if the loss had never occurred.
For example, your regular mortgage payment, association dues, and other ongoing obligations may continue even while you are temporarily displaced.
The policy typically focuses on the additional expenses caused by the covered loss.
Coverage Is Subject to Limits and Time Restrictions
Loss of Use coverage is subject to the policy’s limits, conditions, and time periods.
Some policies may provide coverage based on a stated dollar limit, a percentage of another coverage amount, or a defined period of time. Coverage may also depend on whether the condo is actually uninhabitable because of a covered cause of loss.
Condo Losses Can Involve Delays Beyond Your Unit
In a condominium, repairs can sometimes take longer because the loss may involve both the individual unit and association property.
Building-wide repairs, inspections, contractor access, permits, association approvals, and restoration of common systems can affect how quickly a unit becomes habitable again.
For that reason, Florida condo owners should consider whether their Loss of Use limit would be adequate for an extended displacement after a major covered loss.
Personal Liability Coverage
Personal liability coverage can help protect a Florida condo owner if they are legally responsible for bodily injury or property damage to someone else.
This protection is separate from coverage for the condo itself or the owner’s personal belongings. It is designed to address certain claims and lawsuits arising from personal activities, subject to the policy’s terms, limits, and exclusions.
Examples of Personal Liability Claims
Depending on the circumstances and policy language, personal liability coverage may respond to situations such as:
-
A guest is injured inside the condo and alleges the owner was negligent
-
Water from the insured unit damages another unit and the owner is found legally responsible
-
A child or family member accidentally damages someone else’s property
-
A pet causes injury or property damage, subject to the policy’s animal-related restrictions or exclusions
-
The insured causes accidental injury or damage away from the residence and the claim falls within the policy’s liability coverage
Legal Defense Can Be an Important Part of the Coverage
If a covered liability claim results in a lawsuit, the policy may also provide a legal defense, subject to the policy terms.
Defense costs can become significant even when a claim ultimately does not result in a large settlement or judgment, so the liability portion of an HO-6 policy can be an important part of the overall protection.
Condo Living Can Create Shared-Property Exposures
Condominium owners live in close proximity to other residents and share walls, ceilings, plumbing systems, hallways, and other building components.
That can create liability situations that are different from those of a detached single-family home.
For example, a water loss originating in one unit could potentially damage units below or next door. Whether the owner is legally responsible will depend on the facts of the loss, negligence, applicable law, and the policies involved.
Choose Liability Limits Carefully
The liability limit should be selected based on more than the minimum required by a mortgage company or condominium association.
A condo owner’s income, savings, investments, lifestyle, pets, household members, and other assets may all be relevant when deciding how much liability protection to carry.
Owners who want limits beyond what the HO-6 policy provides may also want to consider a personal umbrella policy, subject to the umbrella insurer’s eligibility and underlying-limit requirements.
🚑 Medical Payments to Others
Medical Payments to Others coverage can help pay certain medical expenses when someone is accidentally injured on or around the insured condo, regardless of who was legally at fault, subject to the policy terms and limits.
This coverage is generally intended for relatively minor injuries and can sometimes help resolve smaller incidents before they develop into a larger liability claim.
Examples of Expenses That May Be Covered
Depending on the policy, Medical Payments to Others may help with expenses such as:
-
Emergency room or urgent care treatment
-
Doctor visits
-
X-rays and diagnostic services
-
Ambulance charges
-
Dental treatment resulting from an accident
-
Other necessary medical expenses related to a covered injury
How It Differs From Personal Liability Coverage
Medical Payments to Others is different from personal liability coverage.
Personal liability generally applies when the insured is legally responsible for another person’s injury or property damage. Medical Payments coverage may apply to certain minor injuries even when fault has not been established.
Coverage Is Usually Limited
Medical Payments limits are typically much lower than personal liability limits and are not intended to cover large or catastrophic injury claims.
The coverage also generally does not apply to injuries suffered by the insured or members of the insured household.
Because policy forms can differ, condo owners should review the specific Medical Payments limit, exclusions, and conditions included in their HO-6 policy.
 An HO-6 policy can combine protection for the condo interior, personal belongings, temporary living expenses, and personal liability, subject to the policy’s terms and limits.
Loss Assessment Coverage
Loss assessment coverage can help protect a Florida condo owner when the condominium association charges unit owners for certain covered property losses that are not fully paid by the association’s insurance.
This can happen when a loss involves common property or association-insured property and the association’s insurance does not cover the entire amount because of a deductible, coverage limitation, or other shortfall.
Under Florida Statute §627.714, a residential condominium unit-owner policy must include at least fce_id=”fce_6ad2442b49928″,000 of property loss assessment coverage for qualifying assessments arising from the same direct loss, subject to the statute and policy terms.
When Loss Assessment Coverage May Apply
Depending on the cause of loss and policy wording, loss assessment coverage may help when an association assesses unit owners for part of a covered loss involving:
-
Common areas
-
Association-owned property
-
Building components insured by the association
-
A portion of an association property-insurance deductible
-
Other covered property losses for which unit owners are assessed
The assessment generally must result from a type of direct property loss that is covered under the unit owner’s policy.
Not Every Special Assessment Is Covered
Loss assessment coverage does not mean every assessment imposed by a condominium association is insured.
Assessments for routine maintenance, reserves, structural repairs unrelated to a covered loss, deferred maintenance, code compliance, capital improvements, or other non-covered expenses generally should not be assumed to qualify.
Coverage depends on why the assessment was imposed, what caused the underlying loss, when the loss occurred, the policy in force at that time, and the terms and exclusions of the HO-6 policy.
The Limit in Effect Before the Loss Matters
Florida law provides that the applicable loss assessment limit is generally the limit that was in effect one day before the occurrence that caused the loss. Increasing the limit after a major event has already occurred does not increase coverage for that event.
Consider Whether the Minimum Limit Is Enough
The statutory minimum does not necessarily mean the minimum is adequate for every condo owner.
A major hurricane, fire, or other loss could leave an association with a substantial deductible or uninsured portion of a loss, and an individual owner’s share of an assessment could exceed the minimum coverage included in the policy.
For that reason, condo owners should review the available loss assessment limits and consider the association’s insurance structure, deductibles, property values, and potential assessment exposure when selecting coverage.
Condo Association Deductibles and Special Assessments
A condominium association’s property insurance can include substantial deductibles, particularly for hurricane or windstorm losses. After a major covered event, the association may need to use reserve funds or assess unit owners to help pay a deductible or other amounts not covered by the association’s insurance.
That does not mean every special assessment charged to a condo owner will be covered by an HO-6 policy.
How Association Insurance Deductibles Work
Florida law permits condominium association property policies to include deductibles established by the association’s board. The deductibles generally must be consistent with industry standards and prevailing practices for comparable condominium communities.
When selecting deductibles, the board may consider available funds, including reserves, as well as predetermined assessment authority.
Under Florida law, property insurance deductibles and certain damages exceeding the association’s insurance coverage are generally treated as common expenses of the condominium, subject to statutory exceptions.
That means unit owners can potentially be responsible for their share of a significant insurance deductible following a major loss.
Example of an Association Deductible Assessment
Suppose a hurricane causes covered damage to a condominium building and the association’s master policy has a large hurricane deductible.
If the association does not have enough available funds to absorb the entire deductible, it may impose an assessment on unit owners to help cover the condominium’s common expense.
Whether an individual owner’s HO-6 loss assessment coverage responds to that assessment depends on the cause of loss, the coverage provided by the unit owner’s policy, the reason for the assessment, and the policy terms and limits.
Not Every Special Assessment Is an Insurance Loss
Condominium associations can impose special assessments for many reasons unrelated to an insured event.
Examples may include:
-
Roof replacement caused by age or deterioration
-
Structural repairs
-
Deferred maintenance
-
Building improvements
-
Reserve funding
-
Painting or exterior renovations
-
Code-compliance projects
-
Routine maintenance
-
Repairs resulting from wear and tear
-
Other capital expenditures
An HO-6 policy should not be expected to pay these assessments simply because the condominium association calls them a “special assessment.”
Loss assessment coverage generally depends on an underlying loss that qualifies under the unit owner’s policy.
Ask Why an Assessment Was Issued
If an association announces a large assessment, condo owners should determine:
-
What caused the expense
-
Whether there was an insured property loss
-
When the loss occurred
-
Which association insurance policy applied
-
How much of the loss was paid by insurance
-
Whether the assessment includes an insurance deductible
-
How the assessment was allocated among unit owners
-
Whether the HO-6 policy in force when the loss occurred provides applicable loss assessment coverage
Florida law requires the stated purpose of a special assessment to be provided to unit owners, and funds collected for the assessment must be used for the specified purpose.
Higher Loss Assessment Limits May Be Worth Reviewing
Because condominium property values and association insurance deductibles can be substantial, the minimum loss assessment coverage included in an HO-6 policy may not be enough for every owner.
Available limits and coverage vary by insurance company, so condo owners should consider the association’s master-policy deductibles and overall insurance structure when deciding how much loss assessment protection to purchase.
 A condominium association deductible or uninsured portion of a covered loss can sometimes result in an assessment to unit owners, but not every special assessment is covered by an HO-6 policy.
Water Damage and Plumbing Losses in a Condominium
Water damage is one of the most important exposures for Florida condo owners because a single plumbing or appliance failure can affect the insured unit, neighboring units, and association property at the same time.
A loss may involve several different questions: what caused the water damage, which property was damaged, who is responsible for maintaining the damaged property, and whether either the association policy or the unit owner’s HO-6 policy covers the loss.
Common Sources of Condo Water Damage
Water losses can result from situations such as:
-
Burst or leaking supply lines
-
Plumbing failures
-
Water heaters
-
Dishwashers and washing machines
-
Refrigerators and ice-maker lines
-
Air-conditioning drain lines
-
Toilets, sinks, and tubs
-
Roof or exterior water intrusion
-
Water originating from another condominium unit
The source of the water does not by itself determine which policy pays. Coverage can depend on the damaged property, the cause of loss, policy language, maintenance responsibilities, and whether negligence contributed to the damage.
Water Damage From Another Unit
If water from a unit above or next door damages your condo, it does not automatically mean the other unit owner’s liability policy will pay for everything.
Your own HO-6 policy may respond to covered damage to property you are responsible for insuring, while the condominium association’s policy may respond to association-insured property. A liability claim against another unit owner generally depends on whether that person was legally responsible for causing the damage.
For that reason, a water loss can involve more than one insurance policy.
When a Unit Owner May Be Financially Responsible
Florida condominium law provides that a unit owner can be responsible for certain repair or replacement costs not paid by insurance when damage results from the intentional conduct, negligence, or failure to comply with condominium rules by the unit owner, household members, tenants, guests, or invitees. That responsibility can also extend to certain property belonging to other unit owners or the association.
This is one reason personal liability coverage on an HO-6 policy can be especially important in a condominium setting.
Sudden Water Damage Is Different From Long-Term Leakage
Condo owners should not assume that every plumbing or water problem is covered.
Many policies distinguish between a sudden accidental water loss and damage caused by long-term leakage, seepage, deterioration, wear and tear, neglect, or inadequate maintenance. The exact wording varies by insurance company and policy form.
A slow leak behind a wall that has existed for an extended period may therefore be treated differently from a pipe that suddenly bursts.
Report Water Losses Promptly
Florida law also addresses situations in which property damage is not reported until after the association’s insurance claim has already been finally resolved or denied as untimely. Prompt reporting can therefore be important when a loss may involve association-insured property.
After discovering a significant water loss, a condo owner should generally take reasonable steps to prevent further damage, notify the appropriate insurer or insurers, and inform the condominium association when common property or other units may be involved.
Because responsibility can be divided between the unit owner, neighboring owners, and the condominium association, water-damage claims are a strong example of why the HO-6 policy should be coordinated with the association’s insurance rather than reviewed on its own.
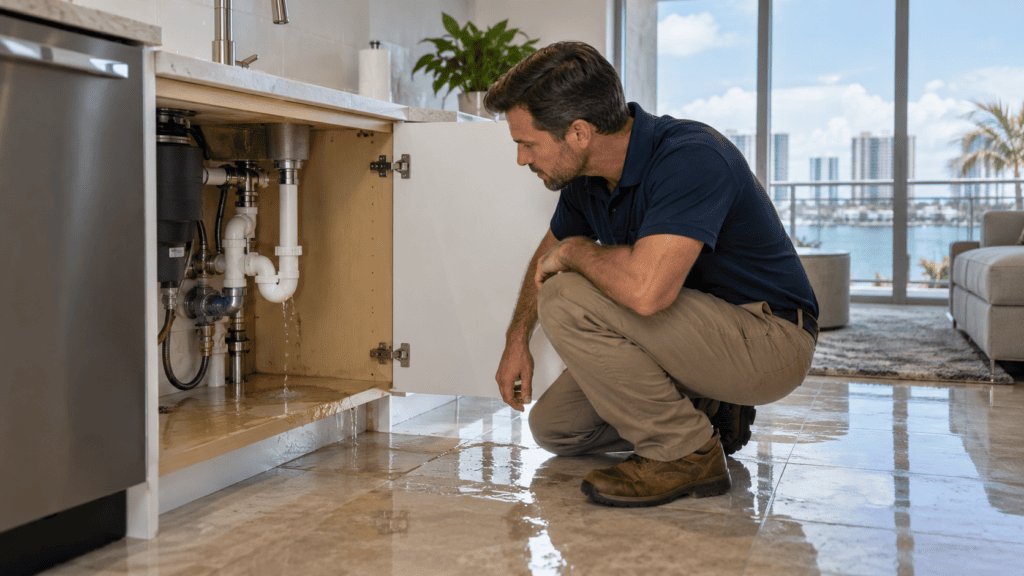 A single water loss can affect the insured unit, neighboring units, and association property, making the cause of damage and insurance responsibility especially important.
⛈️ Hurricane and Windstorm Coverage for Florida Condo Owners
Hurricane and windstorm protection is especially important for Florida condominium owners. A major storm can damage both property insured by the condominium association and property that falls within the individual unit owner’s responsibility.
An HO-6 policy may provide coverage for covered windstorm or hurricane damage to the unit owner’s insured building property and personal belongings, subject to the policy’s limits, deductibles, exclusions, and other terms.
What Is Hurricane Coverage in Florida?
Florida law defines hurricane coverage as coverage for loss or damage caused by windstorm during a hurricane.
It can also include interior damage caused by rain, hail, or similar elements when the direct force of the windstorm first damages the building and creates an opening through which those elements enter. Hurricane coverage does not include flooding.
For example, if hurricane-force winds damage the building and wind-driven rain enters through the resulting opening, applicable property coverage may respond to resulting covered damage.
That is different from water entering because of storm surge, rising surface water, or another type of flooding.
Both the Association and Unit Owner May Have Hurricane Coverage
A condominium hurricane loss can involve more than one insurance policy.
The condominium association’s master policy may cover association-insured building property and common elements, while the individual HO-6 policy may cover property that is the unit owner’s responsibility.
For example, after a major hurricane, the association could have a claim involving the roof, exterior walls, or other association-insured building components while a unit owner simultaneously has a claim involving flooring, cabinets, personal property, or other insured property inside the unit.
The two policies can also have different limits and deductibles.
Wind Damage and Flood Damage Are Not the Same
One of the most important distinctions after a Florida hurricane is the difference between windstorm damage and flood damage.
A hurricane can produce several causes of loss at the same time:
-
High winds
-
Wind-driven rain
-
Storm surge
-
Rising water
-
Heavy rainfall and surface flooding
-
Falling trees or debris
A property policy that covers hurricane wind damage does not automatically provide coverage for flood.
Flood insurance is generally needed to address covered losses caused by flooding, and we will discuss that separately later in this guide.
Do Not Assume the Association’s Hurricane Policy Covers Everything Inside Your Condo
Even if the association has substantial hurricane insurance, its policy does not automatically insure everything belonging to an individual unit owner.
Interior property that is the unit owner’s responsibility, personal belongings, additional living expenses, personal liability, and certain loss assessments may need to be addressed through the individual HO-6 policy or other applicable coverage.
That makes it important to understand both the association’s hurricane insurance and the unit owner’s own policy before a storm occurs.
Review Wind Coverage Before Hurricane Season
Florida condo owners should review whether their HO-6 policy includes windstorm and hurricane coverage, what property is insured, the applicable limits, and the hurricane deductible.
Florida law treats condominium unit-owner policies as residential coverage, and authorized insurers are subject to specific requirements regarding the availability of windstorm coverage and permitted windstorm exclusions. In certain circumstances, a policyholder can elect to exclude windstorm coverage, but statutory requirements apply and a mortgage or lienholder may also need to approve the exclusion.
For most condo owners who rely on their policy for hurricane protection, the next question is equally important: how much must you pay before hurricane coverage begins to respond?
How Hurricane Deductibles Work on Florida Condo Insurance
Florida condo insurance can include a separate hurricane deductible that applies to covered hurricane losses. This deductible can be very different from the standard deductible used for many other property claims.
For Florida personal-lines residential policies, including condominium unit-owner policies, the hurricane deductible generally applies on an annual basis to covered hurricane losses that occur during the same calendar year when the policies are issued by the same insurer or insurer group.
Hurricane Deductibles Are Often Percentage-Based
Florida insurers generally offer hurricane deductible options such as:
-
$500
-
2 percent
-
5 percent
-
10 percent
The percentage is applied to the applicable insured dwelling or structure limit, subject to Florida law and the insurer’s available options. The deductible must also be shown as an actual dollar amount on the policy.
For example, if an HO-6 policy has a $100,000 Coverage A limit and a 2 percent hurricane deductible, the hurricane deductible would be $2,000.
That deductible applies before the insurer begins paying covered hurricane damage under that portion of the policy.
The Hurricane Deductible Is Generally Annual
Unlike a standard deductible that may apply separately to each loss, Florida’s personal-lines hurricane deductible generally applies on a calendar-year basis.
If more than one hurricane causes covered damage during the same calendar year, prior hurricane losses can count toward satisfying the annual hurricane deductible, subject to the policy and statutory rules. Once the annual hurricane deductible has been satisfied, a subsequent covered hurricane loss during that same year may be subject to a smaller deductible or the policy’s non-hurricane deductible, depending on the circumstances.
Because of this, condo owners should report hurricane losses even when the damage appears to be below the deductible and keep documentation showing repair costs and other loss information.
When Does the Hurricane Deductible Apply?
Florida defines the hurricane period for deductible purposes based on National Hurricane Center watches and warnings.
The period begins when a hurricane warning is issued for any part of Florida and ends 72 hours after the termination of the last hurricane watch or hurricane warning issued for any part of Florida.
Damage occurring outside that defined period may be subject to a different deductible depending on the cause of loss and the policy.
The Association Can Have Its Own Hurricane Deductible
A Florida condo owner may also be affected by the hurricane deductible on the condominium association’s master policy.
The association’s deductible can be completely separate from the hurricane deductible on the individual HO-6 policy. After a major hurricane, the association may have a significant deductible on its building coverage, while the unit owner simultaneously has a separate deductible on covered damage to their own insured property.
If the association assesses unit owners for part of its deductible, the owner’s loss assessment coverage may become relevant, but coverage is not automatic and depends on the cause of loss, policy terms, and applicable limits.
Review the Dollar Amount, Not Just the Percentage
A percentage deductible can sound small until it is converted into dollars.
When comparing condo insurance policies, review:
-
The hurricane deductible percentage
-
The actual dollar amount of the deductible
-
The Coverage A limit to which the percentage applies
-
Whether windstorm coverage is included
-
The standard deductible for non-hurricane losses
-
How the deductible interacts with loss assessment coverage
The lowest premium does not necessarily provide the best value if it comes with a hurricane deductible that would be difficult to absorb after a major storm.
🌧️ Flood Insurance for Florida Condo Owners
Standard Florida condo insurance generally does not cover damage caused by flooding. That means an HO-6 policy that protects against hurricane wind damage does not automatically cover water damage caused by storm surge, rising water, or other types of flooding.
For Florida condo owners—particularly those near the coast, rivers, marshes, drainage areas, or other flood-prone locations—flood insurance should be evaluated separately from the HO-6 policy.
What Is Considered a Flood?
Flood insurance is designed to address certain types of water damage that standard condo insurance generally excludes.
Examples can include:
-
Storm surge
-
Rising coastal water
-
Overflow of inland or tidal waters
-
Heavy rainfall that causes surface water to enter the building
-
Flooding affecting multiple properties or a qualifying area
-
Certain mudflow or erosion-related events that meet the policy definition of flood
The exact definition and coverage depend on the flood policy.
A plumbing leak inside the condo, by comparison, is generally not considered a flood simply because it causes significant water damage. Water losses from plumbing systems and flooding are treated differently by insurance policies.
The Condo Association May Have Flood Insurance on the Building
A residential condominium association may purchase flood insurance for the condominium building through the National Flood Insurance Program (NFIP) using a Residential Condominium Building Association Policy, commonly called an RCBAP.
An RCBAP can insure the residential condominium building and certain commonly owned contents. FEMA identifies the RCBAP as the NFIP policy form used by qualifying residential condominium associations to insure the condominium building.
However, the existence of an association flood policy does not necessarily mean an individual condo owner has no flood exposure.
Individual Condo Owners Can Have Their Own Flood Coverage
Under the NFIP, an individual residential condominium unit owner can purchase flood insurance using the Dwelling Form to insure eligible interests in the condominium unit and the owner’s personal contents.
Individual coverage may be worth considering for property such as:
-
Furniture
-
Clothing
-
Electronics
-
Household belongings
-
Certain interior building property or improvements
-
Other eligible property not adequately protected by the association’s flood insurance
Private flood insurance may also be available, with limits, deductibles, coverage features, and eligibility that can differ from an NFIP policy.
Association Flood Insurance and Unit-Owner Flood Insurance Serve Different Purposes
The association’s flood insurance primarily addresses the condominium building and association-insured property.
An individual unit owner may still have exposure involving personal property, interior improvements, deductibles, assessments, or other property that is not fully protected by the association’s flood policy.
For that reason, a condo owner should review:
-
Whether the condominium association carries flood insurance
-
The amount of building coverage maintained by the association
-
The association’s flood deductible
-
What property the association policy insures
-
Whether the unit owner has personal property exposed to flood damage
-
Whether individual building or contents flood coverage is appropriate
-
Whether NFIP or private flood insurance provides the better fit
Flood Zones Do Not Tell the Entire Story
A property does not have to be located in the highest-risk FEMA flood zone to experience flooding.
Heavy rainfall, drainage problems, storm surge, changes in surrounding development, and other conditions can cause flood losses outside areas commonly viewed as high risk.
For that reason, Florida condo owners should consider their actual flood exposure, not simply whether a lender or government program requires flood insurance.
Flood and Hurricane Insurance Should Be Reviewed Together
A hurricane can produce both wind damage and flood damage during the same storm.
The HO-6 policy may respond to covered hurricane wind damage, while a separate flood policy may respond to qualifying flood damage. In a condominium, the association’s property and flood policies may also be involved.
Understanding which policy applies to wind, rain, storm surge, rising water, interior property, and association property before a hurricane occurs can help reduce surprises after a major loss.
Do Upper-Floor Condo Owners Need to Consider Flood Insurance?
Living several floors above ground can reduce the likelihood that floodwater will directly reach your condominium unit, but being on an upper floor does not automatically mean flood exposure can be ignored.
A Florida condo owner should consider the building’s overall flood exposure, the condominium association’s flood insurance, the property located within the individual unit, and how a major flood could affect the building as a whole.
An Upper-Floor Unit Can Still Be Affected by a Flood
Even when floodwater never reaches the interior of an upper-floor condo, a significant flood can affect:
-
Building entrances and lower levels
-
Elevators
-
Electrical or mechanical systems
-
Parking areas and garages
-
Storage areas
-
Common property
-
Access to the building
-
Association-owned equipment and other property
Damage to these areas may make a condominium building difficult or temporarily impossible to occupy even when an individual upper-floor unit has little or no direct floodwater damage.
That does not mean an individual flood policy will necessarily cover every indirect consequence. It does mean that floor level alone should not be the only factor considered when evaluating flood risk.
Review the Association’s Flood Insurance
Upper-floor condo owners should determine whether their condominium association carries flood insurance and understand how that policy applies to the building.
Questions worth reviewing include:
-
Does the association have an NFIP Residential Condominium Building Association Policy or private flood insurance?
-
What building limit is carried?
-
What deductible applies?
-
Is the building insured to an adequate value?
-
What association property is included?
-
Are commonly owned contents insured?
-
What property remains the individual unit owner’s responsibility?
The answers can help determine whether an individual condo owner has a meaningful gap that should be addressed separately.
Personal Property Can Be a Separate Consideration
An individual condo flood policy may provide coverage for eligible personal property and, depending on the policy, certain building property associated with the unit.
For someone living well above the expected flood elevation, the probability of direct flood damage to those belongings may be lower than it is for a ground-floor unit. That difference should be considered when evaluating whether individual flood coverage makes sense.
The decision should therefore be based on the specific unit, building, flood exposure, association coverage, and available policy options, rather than a blanket assumption that every upper-floor condo either does or does not need flood insurance.
Citizens Condo Policies Are Currently Exempt From Its Flood Requirement
There is an important distinction for Florida condo owners insured by Citizens Property Insurance Corporation.
Citizens currently states that condominium unit-owner policies are exempt from its flood-insurance eligibility requirement, including units located above the first floor. This exemption applies to Citizens condominium unit-owner policies even as flood-insurance requirements continue to phase in for many other Citizens residential policies.
That exemption means a Citizens HO-6 policyholder is not required by Citizens to purchase flood insurance simply to maintain the condo unit-owner policy. It does not mean the condominium has no flood exposure or that purchasing flood coverage would never be appropriate.
Required and Recommended Are Different Questions
A lender, association, or other party may have requirements that should be reviewed separately from Citizens’ eligibility rules.
More importantly, whether flood insurance is required and whether it is worth considering are two different questions.
For an upper-floor Florida condo owner, a good flood review should consider:
-
The unit’s floor and elevation
-
Distance from the coast or other water
-
FEMA flood-zone information
-
Storm-surge and rainfall exposure
-
The association’s flood policy
-
The association’s deductible
-
The owner’s personal property and interior improvements
-
Available NFIP and private flood options
An upper-floor location can reduce certain direct flood exposures, but it should be treated as one factor in the decision rather than an automatic reason to dismiss flood insurance altogether.
 Hurricane wind and flooding are separate insurance exposures. An HO-6 policy that covers hurricane wind does not automatically provide coverage for storm surge or rising floodwater.
Citizens vs. Private Condo Insurance in Florida
Florida condo owners may have access to coverage through private insurance companies or, when eligibility requirements are met, Citizens Property Insurance Corporation.
Citizens was created to provide property insurance for eligible Florida property owners who cannot obtain comparable coverage in the private market at qualifying prices. It should generally be viewed as an important market option rather than automatically assuming it is either better or worse than private insurance.
When Might a Condo Owner Be Eligible for Citizens?
For a new Citizens policy, eligibility generally requires one of the following:
-
No comparable coverage is available from a Florida-authorized insurance company, or
-
Comparable coverage available from Florida-authorized insurers costs more than 20 percent above the premium for comparable Citizens coverage
Other underwriting and eligibility requirements can also apply.
This means a condo owner generally cannot choose Citizens simply because they prefer its price if an eligible private-market offer is available within the applicable threshold.
What Can Private Condo Insurance Offer?
Private insurance companies can differ significantly in their underwriting requirements, coverage options, limits, endorsements, deductibles, and pricing.
Depending on the insurance company and condominium, private-market options may offer advantages such as:
-
Higher or more flexible coverage limits
-
Different hurricane deductible options
-
Broader personal property options
-
Higher loss assessment limits
-
Additional water-damage coverage options
-
Scheduled coverage for jewelry and valuables
-
Equipment breakdown or other optional endorsements
-
Different liability limits
-
Additional coverage enhancements or package options
Citizens itself notes that private-market policies may offer more coverage options or less restrictive coverage than Citizens in some situations.
That does not mean every private policy provides broader coverage. The actual policy forms and endorsements must be compared.
What Does Citizens Condo Insurance Cover?
Citizens offers an HO-6 Unit-Owners policy for eligible condominium owners.
Like other HO-6 policies, coverage can address the unit owner’s insured building property, personal property, loss of use, liability, and other covered exposures, subject to Citizens’ policy form, limits, deductibles, exclusions, and available endorsements.
Citizens also maintains specific rating and wind-mitigation provisions for its HO-6 product.
Do Not Compare Condo Insurance on Premium Alone
A lower premium does not necessarily mean two condo policies provide equivalent protection.
When comparing Citizens with a private insurer, condo owners should look at items such as:
-
Coverage A — Building Property limit
-
Personal property limit
-
Replacement cost versus actual cash value
-
Hurricane deductible
-
Other deductibles
-
Water-damage coverage and limitations
-
Loss assessment coverage
-
Additional living expense coverage
-
Personal liability limits
-
Valuable-property limitations
-
Available endorsements
-
Exclusions and restrictions
Citizens’ own eligibility guidance emphasizes comparing the coverage amounts, policy forms, exclusions, and applicable mitigation credits when evaluating private-market and Citizens coverage.
The Best Option Depends on the Individual Condo
For some Florida condo owners, a private insurer may provide the best combination of coverage and price. For others, Citizens may be an important option when qualifying private coverage is unavailable or considerably more expensive.
The better approach is to compare the policies based on the condo itself, association insurance, occupancy, coverage needs, deductibles, eligibility, and total cost rather than choosing an insurance company based on premium alone.
What Does Florida Condo Insurance Typically Not Cover?
A Florida condo insurance policy can provide broad protection, but it does not cover every type of damage or financial loss. Understanding common exclusions is just as important as understanding what the policy covers.
Actual exclusions vary by insurance company and policy form, so the individual HO-6 policy should always be reviewed carefully.
Flooding
Standard condo insurance generally does not cover flooding caused by rising water, storm surge, overflowing bodies of water, or similar flood events.
Separate flood insurance may be needed through the National Flood Insurance Program or a private flood insurer.
Wear and Tear and Maintenance
Condo insurance is generally designed for sudden or accidental covered losses—not routine maintenance or deterioration.
Examples that are typically not covered include:
-
Normal wear and tear
-
Aging or deterioration
-
Rust or corrosion
-
Routine maintenance
-
Mechanical breakdown unless additional coverage applies
-
Damage caused by failure to maintain the property
For example, insurance may cover resulting water damage from certain sudden plumbing failures while not paying to replace the worn-out plumbing component that caused the loss.
Long-Term Leakage or Seepage
Water damage caused by repeated or continuous leakage over an extended period may be excluded or limited.
A pipe that suddenly bursts can be treated very differently from a slow leak that has been occurring unnoticed for months.
Coverage depends on the specific cause of loss and policy language.
Mold
Mold coverage may be limited, excluded, or available only when the mold results from a covered cause of loss.
Policies may also include separate limits for mold testing, remediation, and related expenses.
Condo owners should not assume that all mold damage is automatically covered.
Insects, Rodents, and Pests
Damage caused by termites, insects, rodents, or other pests is generally considered a maintenance or property-management issue rather than an insured sudden loss.
Sewer or Drain Backup
Damage caused by water backing up through a sewer or drain may not be included automatically in every HO-6 policy.
Some insurers offer water backup coverage by endorsement, so this is an important coverage to review when comparing condo policies
Earth Movement
Standard condo policies generally contain exclusions for certain types of earth movement.
Coverage involving sinkholes or catastrophic ground-cover collapse can be governed by specific Florida insurance provisions and policy terms, so condo owners concerned about these exposures should review the coverage offered by their insurer.
Intentional Damage
Insurance generally does not cover intentional damage caused by an insured.
Fraudulent claims and deliberate acts are also excluded.
Business-Related Property and Liability
A standard personal condo policy may provide only limited coverage for business property or business-related liability.
Someone operating a business from a condominium may need separate business insurance depending on the nature of the operation.
Certain High-Value Personal Property
Jewelry, watches, fine art, collectibles, firearms, cash, and other categories of property may be subject to special limits or restrictions.
Additional or scheduled coverage may be needed when the standard policy limits are not sufficient.
Every Special Assessment
Loss assessment coverage does not mean the policy will pay every assessment imposed by the condominium association.
Assessments for maintenance, reserves, structural improvements, deferred repairs, capital projects, or other expenses unrelated to a covered loss generally should not be assumed to be insured.
Rental or Short-Term Rental Activity That Has Not Been Disclosed
A policy written for an owner-occupied condominium may not be appropriate when the property is being rented to others.
Short-term rental activity can create additional underwriting and coverage issues, and the insurance company should be informed about how the condominium is actually used.
Review Exclusions Before a Loss Occurs
Two condo policies with similar coverage limits can contain meaningful differences in exclusions, restrictions, deductibles, and endorsements.
That is why the best time to review what a policy does not cover is before a claim occurs—not afterward.
Renovations, Upgrades, and Betterments in Your Condo
Renovations and upgrades can significantly increase the amount of property a Florida condo owner is responsible for insuring.
A condominium that originally had basic finishes may later include custom cabinets, premium flooring, upgraded countertops, remodeled bathrooms, built-in storage, improved lighting, or other higher-value interior features.
Those improvements can create a larger financial exposure after a covered loss.
What Are Improvements and Betterments?
Improvements and betterments generally refer to upgrades or alterations made to the condominium beyond its original or standard condition.
Examples may include:
-
Hardwood, luxury vinyl, or upgraded tile flooring
-
Custom kitchen cabinets
-
Quartz, granite, or other premium countertops
-
Upgraded bathroom fixtures
-
Built-in shelving or storage
-
Custom closets
-
Decorative wall or ceiling finishes
-
Upgraded lighting fixtures
-
Permanently installed appliances
-
Interior remodeling or structural improvements permitted by the association
The exact treatment of these items depends on the association’s governing documents, applicable law, and the insurance policies involved.
Do Not Assume the Association Will Insure Your Upgrades
A condo association’s master policy may be responsible for certain portions of the building, but that does not necessarily mean it will replace an owner’s upgraded interior finishes after a loss.
For example, the association may be responsible for restoring a portion of the building to its original or standard condition while the unit owner may be responsible for the additional cost of restoring upgraded materials or improvements.
That difference can be significant in a heavily renovated unit.
Coverage A Should Reflect the Current Condition of the Condo
After a renovation, the unit owner should review the Coverage A — Building Property limit on the HO-6 policy.
The limit should reflect the estimated cost to repair or replace the property the owner may be responsible for, including improvements that were added after the condo was originally purchased.
A Coverage A limit that was appropriate years ago may no longer be adequate after a major remodel.
Keep Records of Renovations
It can be helpful to maintain documentation showing the work performed and the value of improvements.
Useful records may include:
-
Contractor invoices
-
Receipts
-
Before-and-after photographs
-
Material specifications
-
Permits
-
Appraisals for high-value improvements
-
Association approvals
These records can help establish what was installed and what it may cost to restore after a covered loss.
Review Coverage Before and After Major Work
Condo owners planning a substantial renovation should review their insurance before construction begins.
Major projects can create temporary construction exposures, increase the value of the finished unit, and sometimes require approval from the condominium association or insurer.
Once the work is completed, the policy should be reviewed again so the coverage reflects the condo’s updated interior.
💎 Jewelry, Art, Collectibles, and Other Valuable Property
A standard Florida condo insurance policy may provide coverage for personal property, but certain high-value items can be subject to special limits, restrictions, or narrower causes of loss.
For condo owners with valuable property, the standard personal property limit may not provide enough protection.
Property That May Need Additional Coverage
Depending on the policy, special limits can apply to items such as:
-
Jewelry and watches
-
Fine art
-
Collectibles
-
Antiques
-
Firearms
-
Silverware
-
Cameras and photography equipment
-
Musical instruments
-
Sports equipment
-
Rare coins or stamps
-
Other high-value personal property
The applicable limits and restrictions vary by insurance company and policy form.
Scheduled Personal Property Can Provide Broader Protection
For eligible valuables, an insurer may offer scheduled personal property coverage or a separate personal articles endorsement.
Scheduling an item can provide a specific insured value and may offer broader protection than relying only on the standard personal property coverage in the HO-6 policy.
Depending on the insurer, scheduled coverage may also reduce or eliminate certain sublimits that would otherwise apply.
Appraisals May Be Required
Insurance companies may require documentation before scheduling higher-value property.
This can include:
-
Recent appraisals
-
Purchase receipts
-
Photographs
-
Certificates of authenticity
-
Detailed descriptions
-
Serial numbers or identifying information
Keeping this documentation current can also help support a claim if the property is later lost, stolen, or damaged.
Review Valuable Property After Major Purchases
A condo owner who purchases new jewelry, artwork, collectibles, or other high-value items should review the policy rather than assuming the existing personal property limit is sufficient.
The best approach is to identify valuable items individually and determine whether the standard HO-6 policy provides enough coverage or whether additional protection should be added.
Primary Residence, Second Home, and Rental Condo Insurance
How a condominium is used can materially affect the type of insurance that should be purchased.
A condo occupied as a primary residence can have different underwriting and coverage needs from a seasonal second home or a unit that is rented to tenants.
Primary Residence Condo Insurance
If you own and live in the condominium as your primary residence, a standard HO-6 unit-owner policy may be appropriate.
Coverage can include:
-
Building property for which you are responsible
-
Personal belongings
-
Additional living expenses
-
Personal liability
-
Medical payments to others
-
Loss assessment coverage
The policy should reflect the value of the interior property, personal belongings, occupancy, and insurance responsibilities established by the condominium association.
Second Home or Seasonal Condo Insurance
Many Florida condominiums are used as second homes or seasonal residences.
These units may be vacant or unoccupied for extended periods, which can affect underwriting and coverage.
Insurance companies may consider factors such as:
-
How often the condo is occupied
-
How long it may remain vacant
-
Whether someone checks the property while the owner is away
-
Water-shutoff or leak-detection systems
-
Security or monitoring
-
Distance from the owner’s primary residence
-
Whether the unit is ever rented to others
A policy written for a second home should accurately reflect how the condo is actually used.
Rental Condo Insurance
A condo that is rented to tenants generally creates different exposures from an owner-occupied residence.
The owner may need coverage for:
-
Interior building property
-
Appliances and furnishings provided to tenants
-
Premises liability
-
Loss of rental income after a covered loss
-
Certain property belonging to the owner
-
Other landlord-related exposures
A standard owner-occupied HO-6 policy may not be appropriate if the condo is regularly rented to others.
Short-Term Rentals Require Special Attention
Vacation rentals and short-term rental arrangements can create additional underwriting concerns.
Not every personal condo policy permits short-term rental activity, and some insurers may restrict or exclude coverage when a property is used through vacation-rental platforms or frequently rented to different occupants.
Any short-term rental activity should be disclosed to the insurance company so the policy accurately reflects the exposure.
Tenants Need Their Own Coverage
A tenant who rents a condo generally does not insure the owner’s interest in the unit.
The tenant should typically consider renters insurance for personal belongings, personal liability, and additional living expenses.
The condo owner’s policy and the tenant’s renters policy protect different interests.
Accurate Occupancy Matters
Insurance applications should accurately describe whether the condominium is:
-
Owner occupied
-
A second home
-
Seasonally occupied
-
Long-term rented
-
Short-term rented
-
Vacant or undergoing renovation
A policy written for the wrong occupancy can create underwriting problems and potential coverage disputes after a loss.
 How a condominium is occupied can affect insurance eligibility, underwriting, coverage, and the type of policy that may be appropriate.
Does a Mortgage Company Require Condo Insurance?
If you finance a condominium, your mortgage lender will typically require insurance that protects its financial interest in the property.
For a condo buyer, that usually means the lender will review both the condominium association’s master insurance policy and the individual unit owner’s HO-6 policy to determine whether the required protection is in place.
Why the Association’s Policy Alone May Not Be Enough
The condominium association generally insures certain portions of the building and common property, but that does not necessarily protect everything inside the individual unit.
A lender may require the unit owner to carry an HO-6 policy because the owner can still be responsible for interior building property, improvements, and other exposures that fall outside the association’s master policy.
What a Lender May Review
Depending on the lender, loan program, condominium, and association coverage, the mortgage company may review items such as:
-
The condominium association’s master policy
-
The amount and type of building coverage carried by the association
-
The association’s deductibles
-
The unit owner’s Coverage A limit
-
Hurricane or windstorm coverage
-
Flood insurance requirements, when applicable
-
The mortgagee clause or lender information shown on the HO-6 policy
-
Whether the policy meets the lender’s minimum insurance requirements
Requirements can vary, so condo buyers should avoid assuming that one standard coverage amount will satisfy every lender.
The Lender’s Minimum Is Not Necessarily the Right Coverage Amount
A mortgage company’s insurance requirement is primarily designed to protect the lender’s interest in the property.
That does not mean the minimum amount required by the lender is enough to fully protect the condo owner.
The owner should also consider:
-
The replacement cost of interior building property
-
Personal belongings
-
Loss assessment exposure
-
Additional living expenses
-
Personal liability
-
Valuable property
-
Flood exposure
-
Hurricane deductibles
-
Renovations and upgrades
Cash Buyers Still Have Significant Exposure
A condo owner who purchases without a mortgage may not have a lender requiring HO-6 insurance, but the financial exposures remain.
Without adequate condo insurance, the owner could be responsible for rebuilding interior property, replacing personal belongings, paying for temporary housing, responding to liability claims, or paying certain assessments out of pocket after a loss.
For that reason, the decision to carry condo insurance should be based on the financial risks associated with owning the unit, not only on whether a lender requires it.
How a Condo Insurance Claim Can Involve Both the Unit Owner and Association
A major condominium loss can involve more than one insurance policy at the same time.
The condominium association’s master policy may be responsible for certain building components and common property, while the individual unit owner’s HO-6 policy may respond to interior property, personal belongings, loss of use, liability, or loss assessment exposures.
One Loss Can Create Multiple Claims
For example, a significant fire, hurricane, or water loss could damage:
-
The building structure
-
Common hallways or mechanical systems
-
Flooring, cabinets, and countertops inside the unit
-
Furniture and personal belongings
-
Property in neighboring units
-
Association-owned property
In that situation, the association may submit a claim under its master policy while one or more unit owners submit separate claims under their individual policies.
Responsibility Depends on What Was Damaged
The key question is not simply where the damage occurred.
What matters is which property was damaged and who is responsible for insuring it.
For example:
-
The association may be responsible for certain structural or common property
-
The unit owner may be responsible for flooring, cabinets, countertops, appliances, interior finishes, and personal property
-
A neighboring unit owner’s liability policy may become relevant if negligence contributed to the loss
-
Loss assessment coverage may become relevant if the association assesses owners for part of an insured loss or deductible
The Cause of Loss Also Matters
Coverage can depend heavily on what caused the damage.
A sudden plumbing failure, hurricane wind loss, fire, flood, long-term leak, or maintenance-related condition can all be treated differently under the policies involved.
That is why the same damaged property can lead to very different insurance outcomes depending on the cause.
The Association’s Deductible Can Affect Unit Owners
Even when the association’s master policy covers the loss, the association may still have a substantial deductible.
If the association assesses unit owners for part of that deductible or for another uncovered portion of the loss, the unit owner’s loss assessment coverage may become important.
Coverage is not automatic and depends on the underlying event, assessment, policy wording, and applicable limits.
Coordination Between Policies Can Be Complicated
Condominium claims can involve questions about:
-
Which policy applies first
-
Which property belongs to the association versus the unit owner
-
Whether negligence is involved
-
Whether the loss is covered or excluded
-
How deductibles apply
-
Whether repairs restore original finishes or upgraded improvements
-
Whether temporary living expenses are covered
-
Whether assessments qualify for loss assessment coverage
Because of this, condo owners should keep copies of both their HO-6 policy and the association’s insurance documents and report significant losses promptly.
Clear Documentation Can Help
After a major loss, it can be helpful to document:
-
The damaged property
-
The apparent cause of loss
-
The date and time the damage was discovered
-
Photos and video
-
Repair estimates
-
Communications with the association
-
Any assessments imposed
-
Receipts for temporary living expenses or emergency repairs
Good documentation can help clarify which policy may be responsible for which portion of the loss.
 One condominium loss can involve the association’s master policy, the unit owner’s HO-6 policy, and sometimes liability or loss assessment coverage.
How Much Does Condo Insurance Cost in Florida?
There is no single price for Florida condo insurance because premiums can vary significantly from one unit and condominium building to another.
The cost of an HO-6 policy depends on factors such as the location of the condo, building characteristics, coverage limits, hurricane deductible, claims history, occupancy, and the amount of property the unit owner is responsible for insuring.
A condo near the coast with higher interior replacement costs can be priced very differently from an inland unit with more modest finishes and lower coverage limits.
What Can Affect the Premium?
Insurance companies may consider factors such as:
-
Condo location
-
Distance from the coast
-
Building age and construction
-
Roof age and condition
-
Wind-mitigation features
-
Claims history
-
Coverage A — Building Property limit
-
Personal property limit
-
Replacement cost options
-
Hurricane deductible
-
Other deductibles
-
Loss assessment coverage
-
Personal liability limits
-
Water-damage coverage
-
Occupancy
-
Whether the unit is a primary residence, second home, or rental property
-
Available discounts
-
Insurance company underwriting requirements
Higher Coverage Limits Can Increase Cost
A heavily upgraded condo may require more building property coverage than a similar unit with basic finishes.
Likewise, higher personal property limits, increased loss assessment coverage, stronger liability protection, scheduled valuables, and additional endorsements can increase premium.
That does not necessarily mean the higher-priced policy is a worse value. The more important question is whether the policy provides the protection the condo owner actually needs.
Hurricane Deductible Choices Can Affect Premium
The hurricane deductible can also influence pricing.
A higher deductible may reduce premium, but it also increases the amount the owner may need to absorb personally after a covered hurricane loss.
For that reason, the lowest available premium should not be the only consideration when choosing a deductible.
Location Matters in Florida
Coastal exposure, wind risk, building characteristics, and local loss experience can affect condo insurance pricing throughout Florida.
Two condos with similar market values may have very different insurance costs because the insurer is evaluating the actual property exposure and coverage being purchased, not simply the sale price of the unit.
Compare Coverage Before Comparing Price
When reviewing Florida condo insurance quotes, make sure the policies are being compared using similar:
-
Building property limits
-
Personal property limits
-
Replacement cost provisions
-
Hurricane deductibles
-
Loss assessment limits
-
Liability limits
-
Water-damage coverage
-
Endorsements and exclusions
A lower premium may reflect less coverage, a higher deductible, or more restrictive policy terms.
The goal should be to find an appropriate balance between coverage, deductible, eligibility, and price.
What Factors Affect Florida Condo Insurance Premiums?
Florida condo insurance premiums are based on a combination of the condominium unit, the building, the coverage selected, and the insurance company’s underwriting guidelines.
Two condo owners in the same city—or even in the same building—can sometimes pay different premiums because their units, coverage limits, deductibles, claims history, and occupancy may not be the same.
Location and Coastal Exposure
Where the condominium is located can have a significant effect on pricing.
Insurance companies may consider factors such as:
-
Distance from the coast
-
Hurricane and wind exposure
-
Local catastrophe risk
-
Flood characteristics
-
Fire protection
-
Historical loss experience in the area
-
Proximity to emergency services
A condominium near the coast may be evaluated differently from a similar unit located farther inland.
Building Age and Construction
The age and construction of the condominium building can also affect underwriting.
Insurers may consider:
-
Year built
-
Construction type
-
Roof age and condition
-
Electrical systems
-
Plumbing systems
-
Building updates
-
Number of stories
-
Wind-resistance features
-
Overall condition of the property
Older buildings may require additional documentation or may have fewer available insurance options depending on their condition and updates.
💨 Wind Mitigation
Florida condominiums with documented wind-resistant construction features may qualify for applicable wind-mitigation credits.
Factors can include:
-
Roof construction
-
Roof-to-wall connections
-
Opening protection
-
Building code compliance
-
Other documented wind-resistant features
The amount of any credit depends on the inspection results, building characteristics, insurer, and policy.
Coverage A — Building Property
The amount of interior building property coverage selected can affect premium.
A condo with custom flooring, high-end cabinetry, upgraded bathrooms, stone countertops, and extensive renovations may need a higher Coverage A limit than a comparable unit with basic finishes.
Personal Property Coverage
Higher personal property limits can also increase premium.
The value of furniture, clothing, electronics, household goods, and other belongings should be considered when selecting coverage.
Deductibles
Deductible choices can influence the cost of the policy.
A higher hurricane or standard deductible may reduce premium, but it also increases the amount the condo owner may need to pay after a covered loss.
The deductible should therefore be chosen based on both premium and the amount the owner could reasonably absorb out of pocket.
Loss Assessment Coverage
Increasing loss assessment coverage can affect premium, but the additional cost may be relatively small compared with the potential financial exposure created by a large association deductible or qualifying assessment.
Available limits vary by insurer.
Water Damage Coverage
Water-related coverage and underwriting can be especially important in condominium buildings.
Insurance companies may consider the age and condition of plumbing systems, prior water losses, building maintenance, and available water-damage endorsements or limitations.
Claims History
Prior insurance claims can affect eligibility and premium.
Insurers may review:
-
Water losses
-
Fire claims
-
Liability claims
-
Theft losses
-
Hurricane or wind claims
-
Frequency and severity of prior losses
Both the individual insured’s claim history and the condominium building’s overall loss experience can be relevant, depending on the insurer.
Occupancy
How the condo is used matters.
A primary residence, seasonal home, second home, long-term rental, or short-term rental can be underwritten differently because each presents a different exposure.
The insurance company should be told how the unit is actually occupied.
Liability Limits and Additional Coverage
Higher liability limits, scheduled valuables, water backup coverage, equipment breakdown, replacement cost options, increased loss assessment coverage, and other endorsements can increase premium.
These additions can also provide important protection, so the goal should not simply be to remove coverage to achieve the lowest price.
Insurance Company Underwriting
Different insurance companies can evaluate the same condo differently.
One insurer may be comfortable with a building that another insurer will not accept, or one may offer broader coverage, different deductibles, or more favorable pricing.
That is one reason comparing multiple insurance options can be particularly valuable in Florida.
How to Compare Florida Condo Insurance Quotes
When comparing Florida condo insurance quotes, the premium is only one part of the decision.
Two HO-6 policies can have similar prices while providing very different limits, deductibles, endorsements, and exclusions. A meaningful comparison should focus on what is actually covered and how the policy would respond after a loss.
Compare the Same Coverage Limits
Start by making sure the quotes use similar limits for:
-
Coverage A — Building Property
-
Personal Property
-
Loss of Use
-
Personal Liability
-
Medical Payments to Others
-
Loss Assessment
If one quote has substantially lower limits, the lower premium may simply reflect less coverage.
Compare Hurricane Deductibles Carefully
Florida condo policies can have different hurricane deductibles.
Review both:
-
The deductible percentage
-
The actual dollar amount
A quote with a lower premium but a much higher hurricane deductible may create a larger out-of-pocket exposure after a storm.
Review Water-Damage Coverage
Water losses are especially important in condominium buildings.
When comparing quotes, review whether the policy includes or limits coverage for:
-
Sudden plumbing failures
-
Water backup
-
Repeated or continuous leakage
-
Mold resulting from a covered water loss
-
Other water-related endorsements or restrictions
The wording can vary significantly between insurers.
Check How Personal Property Is Valued
Confirm whether personal property is settled on:
-
Replacement cost
-
Actual cash value
Replacement cost coverage can provide a stronger recovery after a covered loss because depreciation is generally not deducted once the policy’s replacement requirements are satisfied.
Compare Loss Assessment Coverage
The amount of loss assessment coverage can vary significantly from one policy to another.
This is especially important in Florida because condominium associations can have substantial deductibles and may impose assessments after major insured losses.
Do not assume the minimum available limit is automatically sufficient.
Review Valuable Property Limits
If you own jewelry, art, collectibles, watches, firearms, or other high-value property, check the policy’s special limits.
One insurer may provide more favorable built-in limits, while another may require separate scheduled coverage.
Look at Liability Limits
Personal liability limits should also be compared.
A policy with lower liability limits may cost slightly less, but the difference in protection can be substantial if a serious injury or property-damage claim occurs.
Condo owners with higher assets or greater liability exposure may also want to consider whether the HO-6 policy can coordinate with a personal umbrella policy.
Compare Optional Endorsements
Depending on the insurer, optional coverage may include:
-
Water backup
-
Equipment breakdown
-
Identity theft
-
Increased loss assessment
-
Scheduled personal property
-
Replacement cost enhancements
-
Increased liability limits
-
Other coverage extensions
These endorsements can materially affect the value of the policy.
Review Exclusions and Restrictions
A quote can look attractive until an important exclusion is discovered.
Pay attention to:
-
Windstorm restrictions
-
Water exclusions
-
Mold limits
-
Rental or occupancy restrictions
-
Animal exclusions
-
Business-use limitations
-
Older-building underwriting restrictions
-
Special conditions involving vacant or seasonal units
Make Sure the Association Policy Is Considered
A condo quote should be reviewed in the context of the condominium association’s master insurance.
The amount of Coverage A, loss assessment coverage, and other protection should reflect what the association does and does not insure.
Compare Total Value, Not Just Price
The best Florida condo insurance quote is not necessarily the lowest-priced quote.
A better comparison asks:
-
Are the coverage limits adequate?
-
Are the deductibles manageable?
-
Is wind coverage included?
-
Is water damage treated appropriately?
-
Is loss assessment coverage sufficient?
-
Are valuable belongings adequately protected?
-
Are there important exclusions?
-
Does the insurer fit the building and occupancy?
The goal is to compare coverage quality, financial protection, and price together rather than selecting a policy based on premium alone.
What Information Helps When Getting a Condo Insurance Quote?
Having accurate information available can make the condo insurance quoting process faster and can help avoid coverage gaps caused by incomplete assumptions.
For Florida condo owners, the most useful information generally includes details about the unit, the condominium building, the association’s insurance, and how the property is occupied.
Information About the Condo Unit
Be prepared to provide details such as:
-
Property address
-
Unit number
-
Year built
-
Square footage
-
Floor level
-
Number of bedrooms and bathrooms
-
Whether the unit has been renovated
-
Estimated value of flooring, cabinets, countertops, appliances, and other interior improvements
-
Approximate value of personal property
-
Whether the condo is owner occupied, seasonal, a second home, or rented to others
Information About the Condominium Building
Insurance companies may also ask about the building itself.
Helpful information can include:
-
Construction type
-
Number of stories
-
Roof age and type
-
Building updates
-
Plumbing, electrical, and mechanical systems
-
Wind-mitigation features
-
Fire protection
-
Distance from the coast
-
Flood-zone information
-
Whether the building has had major recent losses
Condominium Association Insurance Information
One of the most important items is the association’s current insurance information.
If available, provide:
-
Master property insurance declaration pages
-
Building coverage limits
-
Association deductibles
-
Hurricane or windstorm deductibles
-
Flood insurance information
-
Loss assessment details
-
Any insurance requirements imposed on unit owners
This helps determine how much HO-6 building property coverage may be appropriate and whether additional protection should be considered.
Prior Insurance and Claims History
Insurance companies may ask for:
-
Current insurer
-
Current coverage limits
-
Expiration date
-
Prior claims
-
Dates and causes of prior losses
-
Whether any repairs have been completed
-
Prior cancellations or nonrenewals
Accurate loss information can help prevent delays during underwriting.
Mortgage Information
If the condo is financed, the lender’s information may be needed so the mortgagee can be shown correctly on the policy.
This can include the mortgage company name and loan information.
Valuable Property Information
If you want additional coverage for jewelry, art, collectibles, watches, or other valuable property, appraisals or receipts may be helpful.
Why Accurate Information Matters
A condo insurance quote is only as reliable as the information used to prepare it.
Providing complete details about the unit, association insurance, occupancy, improvements, and prior losses can help produce a more accurate comparison and reduce the risk of discovering an important coverage issue after the policy is issued.
Florida Condo Insurance for Jacksonville and Northeast Florida
Northeast Florida has a wide range of condominium communities, from high-rise and coastal properties to inland developments, golf communities, active-adult communities, and mixed residential developments.
Condo owners in Jacksonville, Ponte Vedra, Ponte Vedra Beach, St. Augustine, St. Johns County, and surrounding Northeast Florida communities can face very different insurance considerations depending on the building, location, association insurance, occupancy, and individual unit.
 Condo insurance needs can vary across Jacksonville, Ponte Vedra, St. Augustine, and Northeast Florida based on building construction, coastal exposure, association insurance, occupancy, and the individual unit.
Coastal and Wind Exposure
Condominiums closer to the Atlantic coast may face greater exposure to hurricanes, tropical storms, wind-driven rain, and salt-air conditions.
Insurance companies may consider factors such as:
-
Distance from the coast
-
Building construction
-
Roof age and condition
-
Wind-mitigation features
-
Opening protection
-
Number of stories
-
Hurricane deductible
-
Association insurance
-
Prior building losses
A condo in Ponte Vedra Beach or coastal St. Augustine may therefore have different insurance options and pricing from a comparable unit farther inland.
Flood and Storm-Surge Exposure
Northeast Florida condo owners should also consider flood exposure separately from hurricane wind coverage.
Properties near the ocean, Intracoastal Waterway, St. Johns River, creeks, marshes, and low-lying areas may have different flood characteristics.
Even when an individual unit is located above ground level, the building itself can still be affected by flooding involving parking areas, elevators, electrical systems, mechanical equipment, entrances, and common property.
The condominium association’s flood insurance and the potential need for individual flood coverage should therefore be reviewed as part of the overall insurance picture.
High-Rise and Multi-Story Condominiums
Larger condominium buildings can create insurance issues that differ from smaller developments.
Claims may involve:
-
Multiple units
-
Common plumbing systems
-
Elevators
-
Shared mechanical equipment
-
Association property
-
Large master-policy deductibles
-
Extensive water damage
-
Longer repair periods after major losses
The association’s master policy becomes particularly important when evaluating the HO-6 coverage needed by an individual owner.
Seasonal and Second-Home Condos
Northeast Florida also has condominium units used as seasonal residences and second homes.
A unit that remains unoccupied for extended periods may have different underwriting requirements than a primary residence.
Insurance companies may consider whether the condo is monitored while the owner is away, whether water is shut off, whether leak-detection systems are installed, and how frequently the property is occupied.
Condo Insurance Should Reflect the Individual Community
Two condominiums located only a few miles apart can have very different insurance needs because of differences in:
-
Building age
-
Construction
-
Association insurance
-
Master-policy deductibles
-
Coastal exposure
-
Flood exposure
-
Interior improvements
-
Occupancy
-
Claims history
-
Available insurance companies
That is why Northeast Florida condo insurance should be reviewed based on the specific unit and condominium association, rather than relying only on a general estimate based on location.
First Florida Agency works with condo owners in Jacksonville, Ponte Vedra, Ponte Vedra Beach, St. Augustine, St. Johns County, and communities throughout Northeast Florida, while also serving condominium owners across Florida.
What First Florida Agency Reviews When Comparing Condo Insurance
Comparing Florida condo insurance involves more than collecting premiums from different insurance companies.
First Florida Agency reviews the coverage structure, deductibles, association insurance, unit characteristics, occupancy, and other details that can affect how well an HO-6 policy fits the individual condo owner.
Building Property Coverage
We review the amount of Coverage A — Building Property to help determine whether it reasonably reflects the interior property and improvements the unit owner may be responsible for.
This can include items such as:
-
Flooring
-
Cabinets
-
Countertops
-
Fixtures
-
Built-ins
-
Interior finishes
-
Renovations and upgrades
The goal is to avoid relying on an arbitrary limit that does not reflect the actual unit.
Condominium Association Insurance
When available, we also review information from the condominium association’s master policy.
Important items can include:
-
Association building coverage
-
Hurricane or wind deductibles
-
Other property deductibles
-
Flood insurance
-
What property the association insures
-
Potential loss assessment exposure
Understanding the association’s coverage can help identify where the unit owner’s HO-6 policy may need stronger protection.
Hurricane and Wind Coverage
For Florida condo owners, we review whether windstorm coverage is included and how the hurricane deductible works.
That includes looking at:
-
Hurricane deductible percentage
-
Actual deductible amount
-
Windstorm restrictions
-
Coverage available for interior property
-
Potential interaction with association deductibles
Water-Damage Coverage
Water losses can be especially important in condominium buildings.
We review available policy terms relating to:
-
Sudden plumbing losses
-
Water backup
-
Repeated or continuous leakage
-
Mold limitations
-
Other water-related exclusions or endorsements
Policy wording can vary significantly from one insurer to another.
Personal Property
We review whether the personal property limit reasonably reflects the owner’s belongings and whether coverage is written on a replacement cost or actual cash value basis.
We can also identify situations where jewelry, art, collectibles, or other valuables may need additional protection.
Loss Assessment Coverage
Because Florida condominium associations can have substantial deductibles or uninsured portions of certain losses, we review the available loss assessment limits rather than assuming the minimum amount is sufficient.
Liability Protection
We review personal liability limits based on the owner’s overall exposure and whether higher limits may be appropriate.
For condo owners who also carry or are considering a personal umbrella policy, the underlying HO-6 liability limits should also be coordinated with the umbrella insurer’s requirements.
Occupancy
The policy should accurately reflect whether the condo is:
-
A primary residence
-
A second home
-
Seasonally occupied
-
Long-term rented
-
Used for short-term rentals
Occupancy can affect both eligibility and coverage.
Deductibles and Total Cost
We compare deductibles along with premium.
A lower-priced policy may have:
-
A higher hurricane deductible
-
Higher standard deductible
-
Lower coverage limits
-
More restrictive water coverage
-
Lower loss assessment protection
-
Fewer endorsements
For that reason, we focus on the overall value of the policy, not just the lowest premium.
Coverage Differences Between Insurance Companies
Different insurance companies may offer different policy forms, underwriting guidelines, limits, endorsements, and deductibles.
When multiple options are available, First Florida Agency helps compare those differences so condo owners can make a more informed decision about their coverage.
Why Work With First Florida Agency for Condo Insurance?
Florida condo insurance can be more complicated than it first appears because the unit owner’s policy must work alongside the condominium association’s master insurance.
At First Florida Agency, we help condo owners look beyond the premium and review the parts of the policy that can matter most after a loss.
We Review the Unit and the Association Together
A condo policy should not be evaluated in isolation.
When available, we review the association’s insurance information along with the individual HO-6 policy so we can better understand:
-
What the association is responsible for insuring
-
What remains the unit owner’s responsibility
-
The association’s hurricane and property deductibles
-
Whether flood insurance is maintained by the association
-
Potential loss assessment exposure
-
Whether the unit owner’s Coverage A limit appears reasonable
That can help reduce the risk of gaps between the master policy and the individual condo policy.
We Compare More Than Price
Two condo insurance quotes can look similar while providing very different protection.
We compare items such as:
-
Building property coverage
-
Personal property coverage
-
Replacement cost provisions
-
Hurricane deductibles
-
Water-damage limitations
-
Loss assessment coverage
-
Liability limits
-
Valuable-property options
-
Available endorsements
-
Policy exclusions and restrictions
The goal is to help identify the policy that provides the best overall fit—not simply the lowest premium.
We Understand Florida-Specific Condo Exposures
Florida condo owners can face issues involving:
-
Hurricanes and windstorms
-
Flooding and storm surge
-
Water losses
-
Large association deductibles
-
Special assessments
-
Older buildings
-
Seasonal occupancy
-
Second homes
-
Rental use
-
Coastal exposure
These exposures can affect both eligibility and coverage, so the policy should reflect how the unit and condominium community are actually structured.
Local Service With Statewide Reach
First Florida Agency is based in Northeast Florida and works with condo owners in Jacksonville, Ponte Vedra, Ponte Vedra Beach, St. Augustine, St. Johns County, and communities throughout Florida.
Whether the condo is a primary residence, second home, or investment property, we can help review available insurance options and explain the differences in plain language.
Independent Agency Access
As an independent insurance agency, First Florida Agency can evaluate options from multiple insurance companies when available.
That can be especially helpful in Florida, where underwriting appetite, building eligibility, deductibles, and coverage options can vary significantly between insurers.
Get a Florida Condo Insurance Quote
The right Florida condo insurance policy should reflect more than the value of your personal belongings. It should also account for the parts of the unit you are responsible for, the condominium association’s insurance, hurricane and water-damage exposures, liability protection, and potential loss assessments.
First Florida Agency can help you compare available condo insurance options and review important differences in coverage, deductibles, and policy terms.
If available, having the condominium association’s master insurance information can make the review more accurate.
Ready to Review Your Condo Insurance?
Whether you are purchasing a condo, approaching renewal, changing insurance companies, or simply want to make sure your current HO-6 coverage still fits your needs, we can help.
Request a Florida Condo Insurance Quote
or call 904-822-8800 to speak with First Florida Agency.
We serve condo owners in Jacksonville, Ponte Vedra, Ponte Vedra Beach, St. Augustine, St. Johns County, Northeast Florida, and throughout Florida.
Florida Condo Insurance FAQs
What is HO-6 condo insurance in Florida?
HO-6 insurance is designed for individual condominium unit owners. It can help cover certain interior building property, personal belongings, additional living expenses, personal liability, medical payments to others, and qualifying loss assessments, subject to the policy’s limits, deductibles, exclusions, and endorsements.
Does the condominium association’s insurance cover everything inside my condo?
No. The condominium association’s master policy generally insures certain building and common property, but Florida condo owners can still be responsible for flooring, wall and ceiling coverings, electrical fixtures, appliances, water heaters, built-in cabinets, countertops, personal belongings, and other property. The association’s policy and the unit owner’s HO-6 policy should be reviewed together.
Is condo insurance required in Florida?
Florida law does not generally require every condominium unit owner to purchase an HO-6 policy. However, a mortgage lender may require coverage, and a condominium association may have insurance requirements for unit owners. Even when insurance is not required, condo owners can have significant property, liability, loss-of-use, and assessment exposures.
How much building property coverage should I carry on my condo insurance?
The Coverage A limit should reflect the estimated cost to repair or replace the portions of the condo interior for which you may be responsible. This can include flooring, cabinets, countertops, fixtures, built-ins, appliances, and renovations. The appropriate amount is generally based on replacement cost rather than the condo’s market value.
Does Florida condo insurance cover water damage from another unit?
It may, depending on what caused the water damage, what property was damaged, and the terms of the policies involved. Your HO-6 policy may cover certain damaged property you are responsible for insuring, while the association’s policy may cover other building property. Another unit owner’s liability coverage may also become relevant if that owner was legally responsible for the loss.
What is loss assessment coverage on a condo insurance policy?
Loss assessment coverage can help with certain assessments charged by the condominium association after a covered property loss. For example, an assessment may result from part of an association insurance deductible or another insured loss not fully paid by the master policy. Coverage depends on the underlying cause of loss, the reason for the assessment, and the HO-6 policy terms and limits.
Does condo insurance cover every special assessment from the association?
No. Assessments for routine maintenance, reserves, deferred repairs, building improvements, structural projects, or other expenses unrelated to a covered insurance loss generally should not be assumed to be covered. Loss assessment coverage is intended for qualifying assessments arising from covered events, subject to the policy.
Does Florida condo insurance cover hurricane damage?
An HO-6 policy may cover hurricane and windstorm damage to insured property when wind coverage is included, subject to the policy’s hurricane deductible, limits, and exclusions. Hurricane wind coverage does not automatically cover flooding, storm surge, or rising water.
Do I need flood insurance if my condo is on an upper floor?
An upper-floor location can reduce the likelihood of floodwater directly reaching the unit, but it does not eliminate every flood-related exposure. Flooding can damage elevators, electrical and mechanical systems, parking areas, entrances, common property, and lower portions of the building. Condo owners should consider the unit’s location, the association’s flood insurance, and their individual property before deciding whether separate flood coverage is appropriate.
Is condo insurance different for a second home or rental condo?
Yes. Insurance companies may underwrite a primary residence, seasonal condo, second home, long-term rental, and short-term rental differently. The policy should accurately reflect how the condominium is actually occupied because occupancy can affect eligibility, coverage, and pricing.
Is Citizens or private condo insurance better in Florida?
Neither option is automatically better for every condo owner. Citizens may be available when its eligibility requirements are met, while private insurers may offer different coverage limits, deductibles, endorsements, and underwriting options. The better choice depends on the individual condo, association insurance, coverage needs, eligibility, and total cost.
What information do I need to get a Florida condo insurance quote?
Helpful information includes the condo address and unit number, year built, square footage, floor level, occupancy, renovations, estimated value of interior improvements and personal property, prior insurance and claims history, and mortgage information when applicable. Providing the condominium association’s master insurance declarations and deductible information can also help produce a more accurate coverage review.
Let’s Get Started
Florida Condo Insurance Quote Request
"*" indicates required fields
Don’t like forms? Contact us at or email us.
